LNC Independent Contractor Versus Employee Status in Law Firms
Law firms often misclassify legal nurse consultants, risking tax liability and wage claims.
How the two paths differ in practice, before the legal tests apply
A legal nurse consultant sits in a strange spot on a law firm's org chart: clinically trained, legally embedded, and often filed on the payroll wrong from day one. Whether that LNC counts as an independent contractor or an employee turns on a specific set of legal tests, not on what's convenient for the firm's bookkeeper. Get the answer wrong and the firm faces tax liability, wage claims, and, in at least one documented case, a nine-figure judgment that affirmed willful misclassification. Most firms never run the analysis. They default to whichever label feels administratively lighter, then discover years later that the label never mattered.
Start with what the job actually is. An LNC is a registered nurse who reads medical records the way a title examiner reads a deed, hunting for the one fact that changes the whole case. She builds chronologies out of scattered charts, flags deviations from the standard of care, helps attorneys locate expert witnesses, and preps questions for depositions. She doesn't practice law. No client representation, no legal advice, no courtroom argument. She's a clinician working inside a legal shop, translating one professional language into another, and that dual identity is why classification gets complicated. The same work could sit on staff or outside the firm entirely, depending on how the relationship gets built, and most firms build it without ever thinking through the difference.
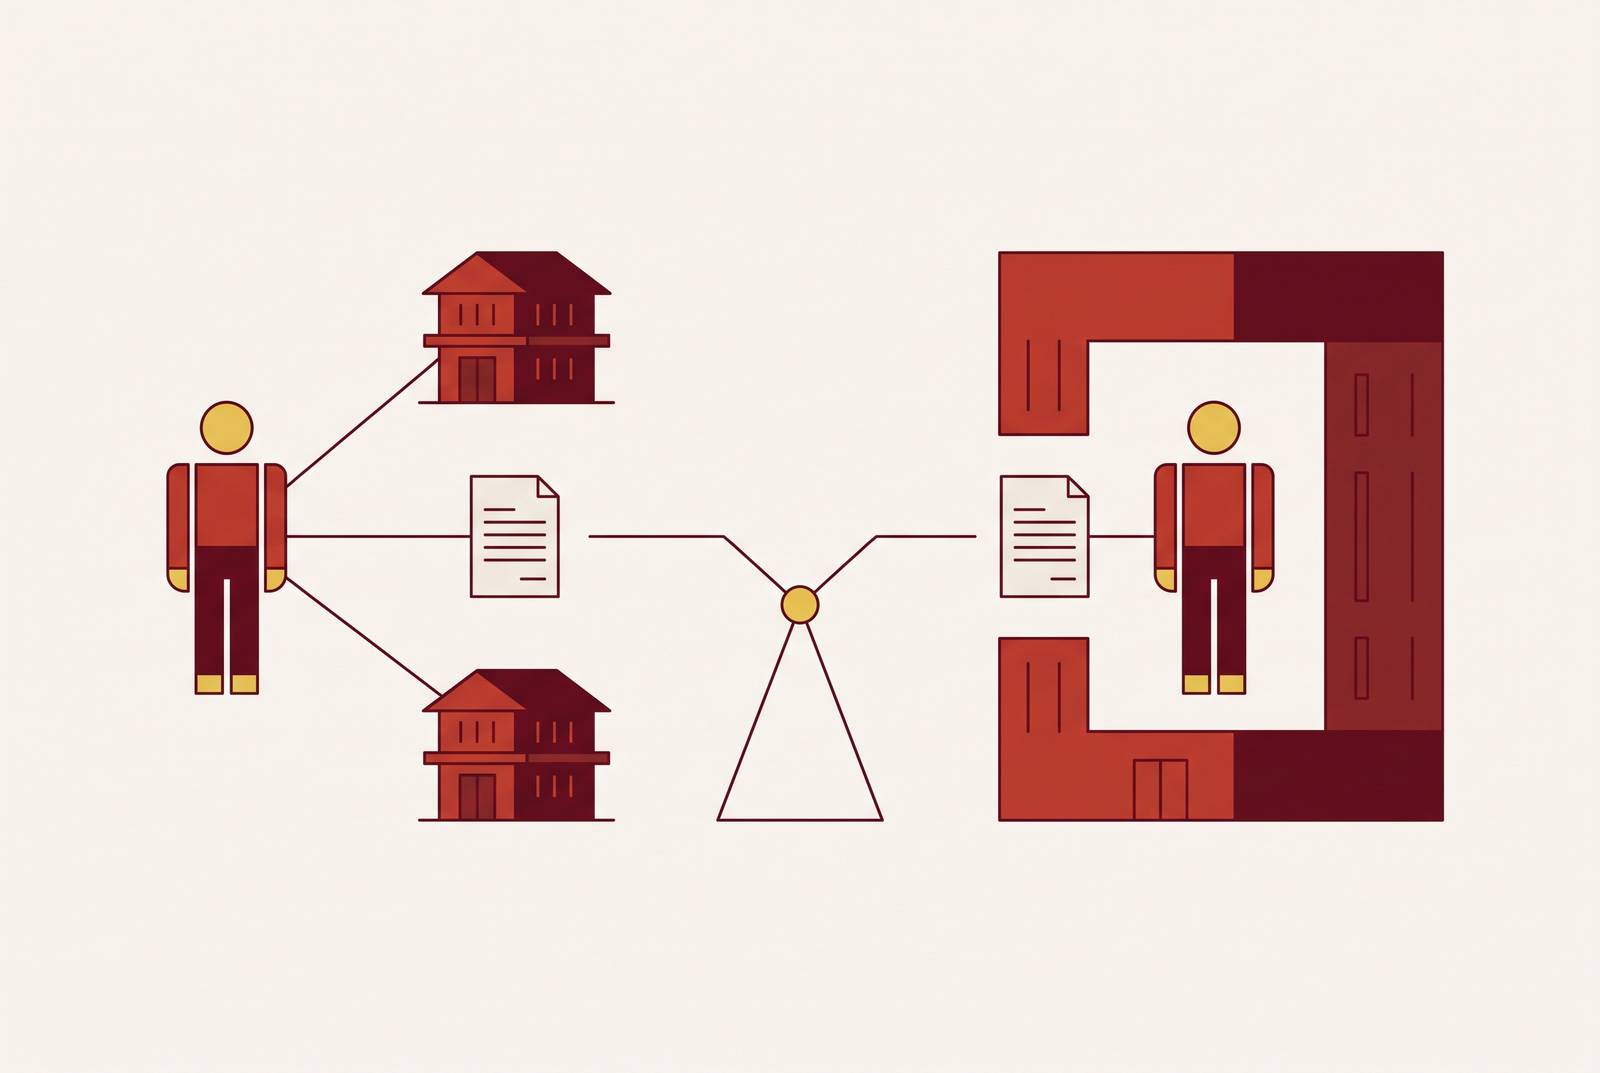
Before any statute or court test enters the picture, the in-house and independent paths already look like different jobs. The gap between them is wider than most firms admit, and having the wrong classification raises pay differences that appear first in the paycheck.
An in-house LNC draws a salary from day one, along with health insurance, paid time off, and usually a retirement match. The firm defines the scope: these cases, this deadline, this schedule. That stability comes at a cost, though. Income growth is capped by the firm's pay scale and its promotion timeline. Annual pay for in-house LNCs typically runs $65,000 to $90,000, and senior roles clear $100,000 only after years of tenure.
The independent path reverses the arrangement. A consultant LNC sets her own schedule, picks her clients, and bills $150 to $175 an hour for case review work, climbing to $250 to $400 an hour for testifying expert work. Revenue scales with caseload and rate, not with a raise cycle, and there's no ceiling on it. That freedom carries a real cost: independent practice demands upfront marketing to build a base of attorney clients, and there's no guaranteed floor under any of it. An independent consultant billing steady hours across the year can out-earn an in-house counterpart several times over, but only after she's built the book of business that makes that possible. Most never get there, and the ones who quit trying usually land back on someone's payroll within a year or two.
A third arrangement sits between the two, and it's the one that muddies classification the most: subcontracting under an established LNC firm or consulting practice. The subcontractor is nominally independent, invoicing rather than drawing a salary, but the day-to-day often looks exactly like employment, since the larger firm assigns cases and sets terms the way an employer would. This is the arrangement regulators catch most often, because the paperwork says one thing and the daily routine says another. Anyone reviewing a firm's LNC roster for risk should start here first, not with the obvious in-house or obvious independent cases.
The three legal tests that govern classification
Federal and state law each apply their own standard to the same working relationship, and a worker can be a contractor under one framework while counting as an employee under another. There's no single national answer here, and a firm cannot safely treat any one test as the final word on classification.
The IRS applies its own multi-factor standard focused on the degree of direction and control the hiring entity exercises over the worker. No single factor decides the outcome, it's a totality assessment, and it's the standard most law firms encounter first because it governs federal tax classification.
A separate federal labor agency runs its own test, and the ground under it has shifted recently. In May 2025, the DOL announced it would stop enforcing the independent contractor rule the Biden administration had issued in 2024. Starting May 1, 2025, DOL enforcement reverted to older "economic reality" principles, the same framework laid out in the 2008 Fact Sheet and the 2019 Opinion Letter. That reinstated standard reflects pre-2024 enforcement principles, and further rulemaking on how it applies going forward remains possible. None of this counts as settled law, though. Further rulemaking is expected, and any firm treating the current posture as permanent is reading more certainty into it than actually exists. The Fourth Circuit's economic realities test from McFeeley, the one applied in the Steadfast case below, sits inside this same analytical tradition.
Then there's the state layer, and for firms in California, New Jersey, Massachusetts, and several other states, it's the hardest one to clear by a wide margin. The ABC Test starts from a presumption of employee status and puts the burden on the business to prove all three prongs: freedom from the hiring entity's control and direction, work performed outside the hiring entity's usual course of business, and an independently established trade or business on the worker's side.
The "B" prong is where law firm arrangements usually collapse, and it deserves more weight than firms give it. If an LNC reviews medical records for a plaintiff's medical malpractice firm, that review work isn't incidental to the firm's business. It is the firm's business. Under that logic, the LNC faces a strong argument against satisfying prong B, no matter how the other two prongs shake out. Firms operating across state lines don't get to pick the friendliest test, either. They face simultaneous exposure under whichever state standards apply to each worker on the roster. A firm with LNCs in three states is running three separate compliance risks at once, not one.
The specific factors that most often tip LNC arrangements toward employee status in law firm settings
Certain patterns are visible in misclassification findings, and they occur because this is how many firms actually run their LNC relationships day to day.
Scheduling control is the first flag, and it's the easiest one for a regulator to spot. A firm that assigns specific cases, sets hard deadlines, and requires the LNC to be available during firm hours is exercising behavioral control, and that control counts as a core factor in every one of the three tests above.
Pay structure matters just as much. An LNC paid a flat hourly or day rate, with no room to negotiate terms and no path toward managerial responsibility, has exactly one lever for earning more: logging additional hours. That's not the same as having a genuine opportunity for profit or loss based on business judgment, which is what separates a contractor from an employee under the economic realities framework. Working longer is simply working longer. It's just working longer.
Exclusivity clauses compound the risk, and they do it in writing. Requiring an LNC to work only for one firm is a documented misclassification signal on its own; spelling that exclusivity out in a signed contract hands an auditor or a court the clearest possible evidence of control. Non-compete clauses barring the LNC from working for other firms after the engagement ends send the same signal, even once the relationship has technically closed.
Longevity closes the loop. Using the same LNC for the same core function year after year, with no other clients on her roster, is a classic audit trigger. Permanence carries real weight under the economic realities test, and a decade-long "consulting engagement" with a single employer starts to look, to a regulator, exactly like a job with a different name stapled to the door.
What the Steadfast Medical Staffing judgment established for law firm–LNC arrangements
The clearest illustration of how these factors converge in court comes from a staffing case, and its facts translate almost line for line to law firm arrangements. Any firm skimming past this one is skipping the closest thing the industry has to a warning label.
Chavez-DeRemer v. Medical Staffing of America, LLC, doing business as Steadfast Medical Staffing (Nos. 23-2176 and 23-2284), involved a company that kept a registry of licensed nurses and placed them with client healthcare facilities under agreements labeled "independent contractor." Those agreements included a 12-month non-compete barring nurses from working for competitors after termination. In a detail that undercut Steadfast's own position at trial, the nurses had signed what the company itself titled an "application for employment" before ever signing the independent contractor agreement that followed it.
A 2017 investigation by a federal labor agency found that Steadfast had willfully misclassified roughly 1,100 certified nursing professionals. The DOL advised the company to reclassify them in 2018. Steadfast didn't.
The Court of Appeals for the Fourth Circuit affirmed a judgment of $9.3 million against the company in July 2025, calling the classification "objectively unreasonable." That figure broke down into roughly $4.8 million in back wages plus about $4.5 million in liquidated damages layered on top, a penalty structure built specifically to punish classification decisions a court finds indefensible rather than merely mistaken.
The relevance to law firms isn't abstract, and it isn't a stretch either. A firm that requires exclusivity, dictates schedules, and calls the arrangement independent while treating the LNC like staff is building the same fact pattern the Fourth Circuit just punished at scale. Nothing about a law office makes that fact pattern less legible to a regulator than a staffing registry does.
The financial and legal penalties that fall on firms, and on the LNC, when classification is wrong
Getting the classification wrong exposes a firm to a long list of liabilities, and few firms tally the full list before making the call. Back employment taxes. Unpaid overtime and minimum wage. Unemployment insurance claims, workers' compensation claims, FMLA violations, disputes over health insurance or retirement plan participation, and interest and penalties stacked on top of all of it. On $100,000 of annual wages carried over three years, cumulative employment tax liability alone on a single worker reaches $135,900 before interest and penalties even enter the picture.
Intent changes the math substantially, and this is the distinction firms should actually be building their policies around. A firm that misclassified in good faith, with a reasonable basis for the decision and proper tax filings along the way, can seek relief under IRS Section 3509, which caps liability at roughly 10.7% to 13.7% of compensation rather than exposing the firm to full employment tax liability. Intentional misclassification forfeits that relief. Steadfast's finding of "objectively unreasonable" classification meant the company had no path to Section 3509 relief at all, and the full judgment landed accordingly.
State law stacks its own exposure on top of the federal liability. California imposes civil penalties for willful misclassification that can reach significant sums per violation. New York exposes employers to liability for unpaid unemployment insurance contributions, workers' compensation contributions, state withholding taxes, back wages, statutory interest, and civil fines tied to improper payroll recordkeeping.
The exposure doesn't end when the engagement does, either. A disgruntled LNC can allege misclassification well after the relationship ends, even having signed a contractor agreement at the outset and operated under that label for years. That agreement isn't a waiver, and it never was one. Courts and regulators evaluate the actual working relationship, not the label the parties chose for it at the start, and a firm's classification decision stays exposed to challenge long after the engagement letter gets filed away and forgotten.